Zero down payment
Buy a home without saving for years first. Eligible veterans and active-duty families can finance with no down payment required.
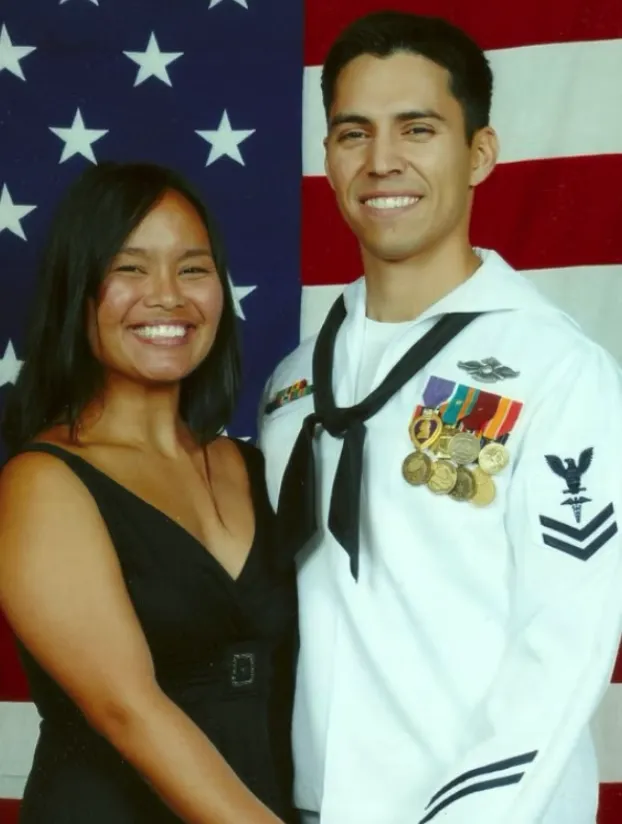
I'm Jonathan — 3x combat veteran, Purple Heart recipient, and Mortgage Loan Originator — I've used my own VA loan multiple times and now help fellow veterans do the same.
I spent 20 years in combined military and federal service, and I've personally used my VA loan benefit multiple times, including selling a home, paying it off, and restoring my entitlement to buy again with zero down.
I'm not learning this from a training manual. I've lived every step I teach — which is why I focus specifically on helping active-duty service members, veterans, and military spouses understand exactly what this benefit can do for them, in plain language, with no pressure to move faster than you're ready for.
Four clear steps, with one person guiding you through every one of them. It all starts with a short call with Jonathan.
Start here
A short, no-pressure phone call about your homebuying goals, your timeline, and whether now is the right time to use your VA loan benefit.
When you're ready
Jonathan gets your application started with you, so you always know what comes next and why.
Know your numbers
A credit pull shows your real numbers, so your options are built on facts, not estimates. Jonathan walks you through every detail.
Your game plan
Typically within 24 to 48 hours of your credit review, a 20-minute consultation covers your options, your numbers, and your next steps. Plain language, no pressure.
No cost and no obligation. Just a conversation about your options.
Your VA loan benefit is one of the strongest paths to homeownership available. Here's what it can do for you.
Buy a home without saving for years first. Eligible veterans and active-duty families can finance with no down payment required.
VA loans never carry monthly PMI or MIP, even with zero down. FHA and most low-down-payment conventional loans charge it.
The VA sets no minimum credit score. Lenders set their own standards, which are often more flexible than conventional loans.
The VA restricts certain fees lenders can pass on to you. Sellers can also help, with concessions of up to 4% toward your costs.
With full entitlement, the VA sets no cap on how much you can borrow, as long as you qualify. Partial entitlement ties to your county's conforming loan limit.
When you sell, a qualified buyer may be able to take over your VA loan and its terms. Most conventional loans can't offer that.
Jonathan will walk you through your eligibility, your entitlement, and your real numbers on one short call.
Benefits are subject to VA eligibility, entitlement, credit, and lender approval. A VA funding fee may apply unless you're exempt.